Always Evolving: DSCR Expanded Just Got Bigger
The market keeps moving. So do we. At PwrTPO, every enhancement we make comes back to one goal: giving mortgage professionals one more yes for their clients. This month, that means meaningful upgrades to our DSCR Expanded Program, including higherloan amounts and new flexibility for short-term rental investors, with more onthe way.
Why investor lending matters right now
Investor lending has become one of the most important growth areas in Non-QM. According to Optimal Blue data reported by HousingWire, investor and DSCR loans rose from 28% of Non-QM production in August 2025 to 35% in August 2026. Bank of America Securities projects total Non-QM originations will reach $175 billion in 2026, up from $108 billion in 2025, with DSCR and investor products making up about half of Non-QM collateral, according to HousingWire. Looking ahead, Cotality expects investors to keep accounting for more than a quarter of home purchases through 2027 (ScotsmanGuide), even as the MBA projects total single-family originations will dip about 5% in 2027 (HousingWire).
For mortgage professionals, that trend shows up every day: more clients asking about rental properties, more self-employed buyers building portfolios and more scenarios that don't fit a conventional box. The right investor program, with the right limits, is now a core part of any Non-QM toolkit.
A quick refresher: how DSCR qualification works
DSCR stands for debt service coverage ratio. Instead of verifying personal income with tax returns, W-2s or pay stubs, a DSCR loan compares the property's rental income to its monthly housing expense, which includes principal, interest, taxes, insurance and any association dues. The ratio shows whether the property can carry its own debt.
Because qualification centers onthe property's cash flow, DSCR is a strong fit for:
• Self-employed borrowers whose tax returns reflect significant write-offs
• Investors with multiple properties and complex income
• Clients focused on growing a rental portfolio rather than buying a single home
Credit, reserves and property eligibility still matter, so each file reviews the borrower's full profile alongside the property's income.
Higher loan amounts: up to $3M on purchase and rate/term
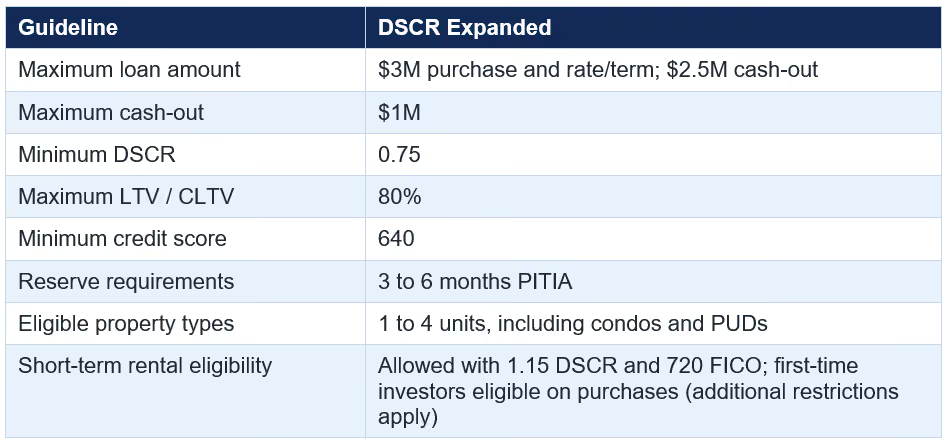
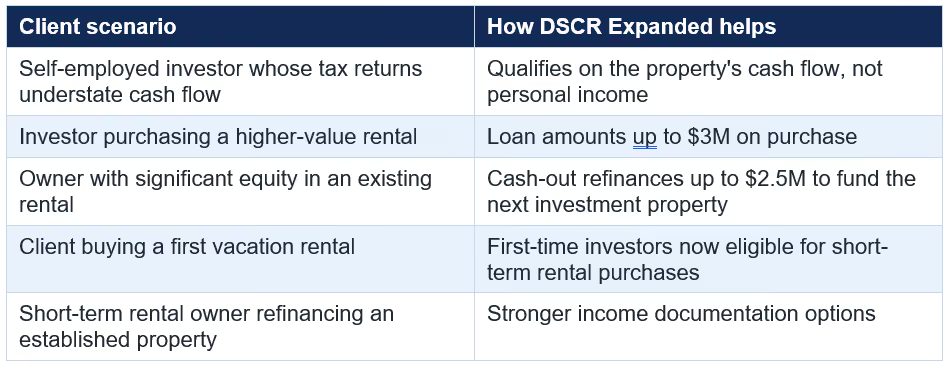
DSCR Expanded now goes up to $3M on purchase and rate/term refinance transactions, and up to $2.5M on cash-out refinances. Here's where the higher limits make a difference:
• Higher-value markets. In many metros, quality rental properties have outgrown lower loan limits. The higher ceiling keeps those deals within the program.
• Stepping up in size. Investors moving from a starter rental to a larger property no longer have to restructure the deal around a lower cap.
• Rate/term refinances. Owners of higher-value rentals have more room to restructure existing financing.
• Cash-out refinances up to $2.5M. Cash-out refinance loan amounts go up to $2.5M, with up to $1M in cash-out proceeds. Investors with substantial equity can put it to work, whether that means funding the next acquisition or improving a property they already own.
DSCR Expanded at a glance
Short-term rentals: more doors open
Short-term rental financing has traditionally been one of the more challenging investor scenarios. Prior hosting or landlord experience requirements, conservative occupancy assumptions and limited ways to document income on an existing rental have all kept deals off the table. Our updates address each of these.
First-time investors can now purchase short-term rentals. Experience requirements are often the biggest hurdle for a client buying a first vacation rental. With this change, clients ready to purchase their first cabin, lake house or beach rental now have a path through DSCR Expanded.
More flexible AirDNA occupancy guidelines. On short-term rental purchases, projected income often comes from AirDNA, a third-party data provider that estimates a property's revenue based on comparable short-term rentals nearby. Occupancy assumptions directly shape that projection, so more flexible guidelines mean more properties in more markets can show the income needed to qualify.
Stronger income documentation on STR refinances. For owners who already operate a short-term rental, the property's actual performance is often the best evidence of its income. Our updated documentation options give that income stronger support at refinance.
One practical tip: short-term rental rules vary widely by market. Encourage clients to confirm local permits, zoning and any HOA restrictions before writing an offer.
Scenarios to watch for in your pipeline
Recently closed DSCR loans
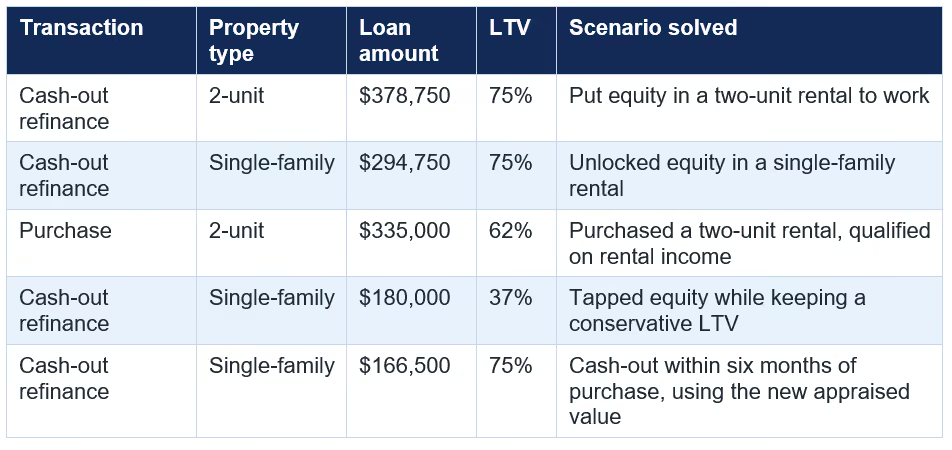
Here's a look at five DSCR loans our partners recently closed with PwrTPO. Each one qualified on the property's cash flow, not the borrower's personal income.
Questions that start the conversation
Many investor deals begin with a single question. Consider adding these to your client conversations:
• Do you own, or plan to buy, a property you'll rent out?
• Have you thought about a vacation rental in an area you already know well?
• How much equity is sitting in your current rental properties?
• Has income documentation ever held back a purchase you wanted to make?
Why mortgage professionals choose PwrTPO for Non-QM
As investor lending grows, so does the industry's focus on underwriting quality and verification. Our partners count on:
• Underwriters with 15+ years of experience reviewing every file, with no AI underwriting decisions
• An average of about 14 days from submission to clear to close
• 100% U.S.-based operations
• 150+ years of combined TPO experience
• Non-QM PwrUp Sessions that help your team identify and structure investor scenarios
More is on the way
We told you we're always evolving. Two new Non-QM programs launch in November, which means even more ways to say yes. Stay tuned for the official announcement and full program details.
Now is a great time to schedule a Non-QM PwrUp Session and give your team even more tools to say yes. Contact your PwrTPO Account Executive to get started.
Equal Housing Lender | NMLS ID #1124061. Program guidelines subject to change.