Buydowns: Starting the Right Conversation with Borrowers and Realtor Partners
Buying a home is about more than getting to the closing table. For many borrowers, it is also about getting comfortable with everything that comes after it.
Moving expenses. New furniture. Repairs. Projects. And all the other costs that have a way of showing up shortly after the keys are handed over.
That is where understanding the different ways to structure a mortgage can create another opportunity to help.
Buydowns can give mortgage professionals another option to explore with borrowers while also creating a valuable conversation with Realtor partners. But before deciding whether a buydown makes sense, it is important to understand what the borrower is trying to accomplish.
Temporary vs. Permanent: Two Different Buydown Conversations
Not every buydown works the same way.
When someone talks about "buying down the rate," they may be referring to either a permanent buydown or a temporary buydown. Both can provide a benefit to the borrower, but the right conversation depends on what the borrower is trying to accomplish.
With a permanent buydown, discount points are paid at closing to reduce the note rate on the mortgage. The borrower receives the benefit of that lower rate for as long as they keep that mortgage.
A temporary buydown works differently. Funds are set aside at closing to reduce the borrower's effective payment for a specific period at the beginning of the loan. Once the buydown period ends, the borrower makes the full payment based on the note rate.
That makes the borrower's goals an important part of the conversation.
Are they more focused on reducing their payment during the first few years of homeownership? Or are they looking for a benefit that extends over the life of the loan?
There is not one answer that fits every borrower. Understanding their short term and long-term needs can help you explore which options may make sense for their scenario.
So, How Does a Temporary Buydown Work?
A temporary buydown uses funds set aside at closing to reduce a borrower's effective mortgage payment for a specific period at the beginning of the loan.
The important word is temporary.
The borrower's loan is still based on the full terms of the mortgage. The buydown provides a lower payment during the designated buydown period before the borrower transitions to the full payment.
Think of it as a softer landing into homeownership rather than a change to the permanent terms of the loan.
What Do 1/0, 2/1 and 3/2/1 Mean?
The name of the buydown tells you how the payment structure changes over time.
1/0 Buydown
Provides a reduced payment during the first year. The borrower transitions to the full payment in year two.
2/1 Buydown
Provides the greatest payment reduction during the first year, a smaller reduction during the second year and then transitions to the full payment in year three.
3/2/1 Buydown
Provides a stepped payment structure over the first three years before transitioning to the full payment in year four.
The longer the buydown period, the longer the borrower has before reaching the full payment.
Why This Conversation Can Matter to Borrowers
Every borrower has a different financial picture, and a temporary buydown is not about making a home affordable that otherwise would not be.
Instead, it can provide some additional breathing room during the early years of homeownership.
That may be especially meaningful for borrowers who are balancing the upfront expenses that often come with purchasing and settling into a home.
The key is helping borrowers understand both sides of the equation: the benefit they receive during the buydown period and the payment they will be responsible for when that period ends.
A good buydown conversation should never stop at, "Your initial payment is lower."
It should also include, "Here is what happens next."
That kind of transparency helps borrowers understand the full picture and make a more informed decision about what works for their goals.
Another Conversation to Have With Your Realtor Partners
Buydowns can also give mortgage professionals another way to add value to their Realtor relationships.
When a seller is willing to contribute toward a transaction, the conversation does not always have to begin and end with reducing the purchase price.
Depending on the borrower, property and transaction, a seller paid temporary buydown may be another option worth exploring.
That gives you an opportunity to work alongside your Realtor partner before an offer is written or during negotiations to talk through questions like:
• Could a seller paid buydown benefit this buyer?
• Which temporary buydown structure may make sense for the transaction?
• How can we clearly explain the benefit to the borrower?
• What does the borrower need to understand about the payment after the temporary buydown ends?
Those conversations can help everyone understand the financing strategy before decisions are made.
And they give you another opportunity to be the mortgage resource your Realtor partners can bring into the conversation.
Temporary Buydown Options With PwrTPO
PwrTPO Lender Paid 1/0 Buydown
PwrTPO offers a lender paid 1/0 temporary buydown on eligible Conventional programs, giving our partners another option to explore with qualified borrowers without requiring the seller to fund the buydown.
Seller Paid Temporary Buydowns
When the seller funds the temporary buydown, PwrTPO offers:
1/0 | 2/1 | 3/2/1
Seller paid temporary buydowns are available across most Conventional and Government loan programs, giving you more ways to explore a financing structure that fits your borrower's needs.
They can also create another opportunity for buyers, sellers, Realtors and mortgage professionals to work together toward the right solution.
Temporary Buydown Options at a Glance
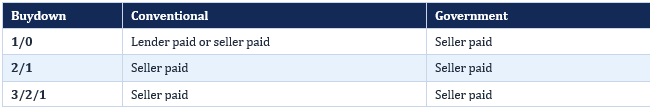
While the 1/0 can be structured as either lender paid or seller paid on eligible Conventional programs, Government programs require the 1/0 to be seller paid. The 2/1 and 3/2/1 are seller paid only.
Start With the Borrower, Not the Buydown
A permanent or temporary buydown is not automatically the right answer for every borrower or every transaction.
And that is exactly why the conversation matters.
Instead of starting with a particular buydown structure, start with the borrower.
What are they trying to accomplish? Are their needs more focused on the first few years of homeownership or the longer term? Is there a seller contribution available? What options could be considered based on the complete loan scenario?
Then build from there.
Your PwrTPO Account Executive can help you review the scenario, explore eligible buydown options and work through how different structures may apply before you have the conversation with your borrower or Realtor partner.
Because the goal is not simply to offer another loan feature.
It is to give you another way to bring solutions to your borrowers, value to your Realtor relationships and the right people to work through the possibilities with you.
Have a scenario? Connect with your PwrTPO Account Executive and let's take a closer look.
This document is intended solely for the information and use of Third Party Originators (TPO), Brokers, and Independent Mortgage Bankers (IMB). It is not for borrower use or distribution. Information is subject to change without notice. Program eligibility and restrictions apply.
Equal Housing Lender | NMLS ID #1124061
Sources
• Fannie Mae Selling Guide, Temporary Interest Rate Buydowns
• Freddie Mac Single-Family, Mortgages with Temporary Subsidy Buydown Plans